Key takeaways
- AMV Assurances posts the highest cap in the comparison in 2026: 2,000 euros, helmet replaced at new value for 24 months and airbag vest included, all bundled from the third-party + theft formula upwards. On the sole criterion of the insured amount, it is the policy that pays back the most.
- Mutuelle des Motards (1,600 euros, no depreciation in year one) and April Moto (1,500 euros) complete the podium. For recent gear, the absence of depreciation in the first year makes Mutuelle des Motards particularly rewarding. Generalist insurers cap their payouts between 800 and 1,200 euros.
- A full set of gear (helmet, gloves, jacket, boots, airbag) represents 1,000 to 2,500 euros of investment. Without this essential guarantee, none of it gets reimbursed after a claim.
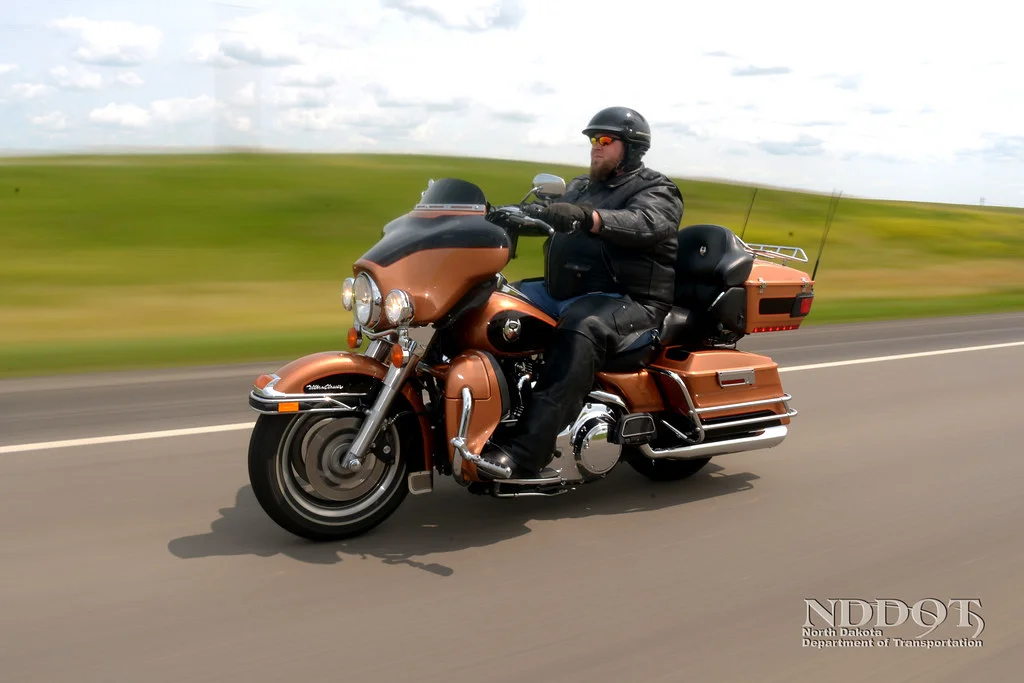
A decent helmet costs 400 euros, a certified jacket 300, an airbag vest 600. All in, a rider carries 1,000 to 2,500 euros on their back. And the basic cover of a motorcycle policy pays for none of it: without an explicit motorcycle gear coverage clause, the insurer reimburses the bike, not what you wear. The level of this guarantee varies threefold between companies. Here is the top 7 insurers on this exact criterion, a direct companion to our young driver 125 insurance ranking.
The top 7 gear guarantees in one table
| Rank | Insurer | Cap | Availability |
|---|---|---|---|
| 1 | AMV Assurances | €2,000 | Included from third-party + theft |
| 2 | Mutuelle des Motards | €1,600 | Included or €40/year option |
| 3 | April Moto | €1,500 | €35/year option |
| 4 | Direct Assurance (AXA) | €1,200 | Included in comprehensive |
| 5 | Macif | €1,000 | €25/year option |
| 6 | Allianz | €1,000 | €30/year option |
| 7 | MAAF | €800 | €30/year option |
Caps range from 800 to 2,000 euros depending on the insurer.
1. AMV Assurances: a 2,000 euro gear cap
AMV Assurances, a two-wheeler specialist broker since 1974, covers helmet and gear up to 2,000 euros, the highest amount among the 7 policies studied. The guarantee is also included from the third-party + theft formula. The helmet is replaced at new value for 24 months, and airbag vests fall within the covered scope.
AMV pros
- 2,000 euro cap, the highest among the 7 insurers compared
- 24-month new-value clause on the helmet, twice as long as anywhere else
- Electronic airbag covered at no extra premium
- Guarantee included from third-party + theft, no need for comprehensive
- No specific deductible on the gear line
2. Mutuelle des Motards: zero depreciation in year one
Founded by the FFMC riders’ federation in 1983, Mutuelle des Motards caps its gear guarantee at 1,600 euros but applies a distinctive rule: no depreciation at all during the first year, whatever the damaged item. For a rider with recent gear, it is a rewarding option: a new helmet and jacket destroyed within the year are reimbursed at 100% of their price. Consistent with its safety-first positioning, the riders’ mutual also covers airbags and rewards CE-certified gear.
Mutuelle des Motards pros
- Zero depreciation for 12 months on all gear
- Airbag covered by default, including 700 euro electronic models
- 5 to 10% premium discount for full CE-certified equipment
- Claims assessed by rider technicians
3. April Moto: a 1,500 euro cap for 35 euros per year
April Moto charges 35 euros per year for its gear guarantee with a 1,500 euro cap and a 12-month new-value clause. It suits riders who want a straightforward option without a specialist broker’s full package. Claims are filed in 2 taps from the app, with photos of the damaged gear.
April Moto pros
- 1,500 euro cap for only 35 euros per year
- 12-month new-value clause on all gear, not just the helmet
- Claim filing and tracking 100% in-app
4. Direct Assurance: gear included in comprehensive cover
Direct Assurance, the AXA group’s online pure player, includes a 1,200 euro gear guarantee in its comprehensive formula. The positioning suits riders already set on maximum cover.
Direct Assurance pros
- 1,200 euro cap included in comprehensive at no extra cost
- 24-hour online claim handling, digital accident report built in
- Backed by the AXA group’s financial strength
5. Macif: the cheapest option in the comparison
Macif sells a gear option at 25 euros per year, the cheapest in this comparison, with a 1,000 euro cap.
Macif pros
- The cheapest option in this comparison (25 euros per year)
- Stacks with the multi-policy member discount (up to 15%)
- Physical branch network for claim follow-up
6. Allianz: strong personal injury cover
Allianz France covers helmet and gear up to 1,000 euros, paired with rider personal injury cover that climbs to 350,000 euros.
Allianz pros
- Gear option paired with 350,000 euros of personal injury cover
- Extended coverage across Europe + Morocco + Tunisia included
- Premium legal assistance in case of payout disputes
7. MAAF: an accessible option with a physical network
MAAF offers a gear guarantee capped at 800 euros, backed by a network of 700 branches. Airbag vests can be covered through a dedicated extension.
MAAF pros
- Network of 700 physical branches to handle a claim face to face
- Fee-free monthly payment of the option
- Car + motorcycle bundle at -10%
What motorcycle gear coverage actually pays for
By definition, a gear guarantee reimburses the protective items worn at the time of the accident: helmet, gloves, jacket, trousers, boots and airbag vest. Note that motorcycle accessories fixed to the bike (top case, heated grips, tall screen) fall under a separate accessories guarantee in the insurance contract, not to be confused at subscription time. Three points to check before signing.
- Invoices rule. Without proof of purchase, most insurers apply a flat allowance of 150 to 300 euros. Keep your receipts, even as photos.
- Depreciation changes everything. A 10 to 15% yearly write-down means a 400 euro jacket bought 4 years ago gets reimbursed 160 to 240 euros. New-value clauses (AMV, Mutuelle des Motards, April) neutralise that write-down for 12 to 24 months.
- CE-certified gloves have been mandatory in France since the November 2016 decree. Riding without certified gloves can justify a payout reduction, including on other items.
According to the French road safety observatory ONISR’s 2024 report, motorised two-wheeler riders account for 22% of road fatalities for less than 2% of traffic. Gear is the rider’s only protection, which explains why specialist insurers make it a central selling point. The choice of bike matters too: an urban scooter exposes you less than a sportbike, as detailed in our best 125 scooter comparison.
For new licence holders, gear coverage is negotiated together with the main policy. Our best A2 motorcycle guide covers the overall insurance budget to plan for a first big bike.
Frequently asked questions
Which insurers offer the best motorcycle gear coverage?
On the cap criterion, AMV Assurances comes first with 2,000 euros, ahead of Mutuelle des Motards (1,600 euros, zero depreciation in year one) and April Moto (1,500 euros). Then come Direct Assurance (1,200 euros), Macif and Allianz (1,000 euros each), and MAAF (800 euros). The insured amount is not the only angle: for gear bought recently, Mutuelle des Motards’ zero-depreciation rule is particularly rewarding.
How much does motorcycle gear coverage cost?
Between 25 and 40 euros per year when sold as an option (Macif 25 euros, Allianz and MAAF 30 euros, April Moto 35 euros, Mutuelle des Motards 40 euros). At AMV, it comes included from the third-party + theft formula at no extra cost, and at Direct Assurance it is included in comprehensive cover.
Does gear coverage include airbag vests?
Not always. AMV and Mutuelle des Motards cover airbags by default, including 600-800 euro electronic models. At MAAF, the airbag can be covered through a dedicated extension. Check the exact list of covered items before subscribing, as the airbag is often the most expensive piece after the helmet.
How do you get your gear reimbursed after a crash?
File the claim within 5 working days with photos of the damaged gear and original purchase invoices. Without invoices, the payout drops to a flat allowance of 150 to 300 euros depending on the company. The insurer then applies the contractual depreciation (0 to 15% per year) unless a new-value clause is still running.